XAUUSDPRKIRA: A Long-Only XAU/USD Methodology — 4,986 Trades, 76% Long Win Rate and a 2.18 Profit Factor
By Piyush Ratnu | Quant Gold Strategist
In trading, a methodology becomes more meaningful when its performance can be examined through actual statistics rather than judged only by individual winning trades. My objective with XAUUSDPRKIRA is to demonstrate a highly specific approach to Spot Gold: trading XAU/USD exclusively from the BUY side, repeatedly identifying lower-price opportunities rather than relying on short selling to generate performance.
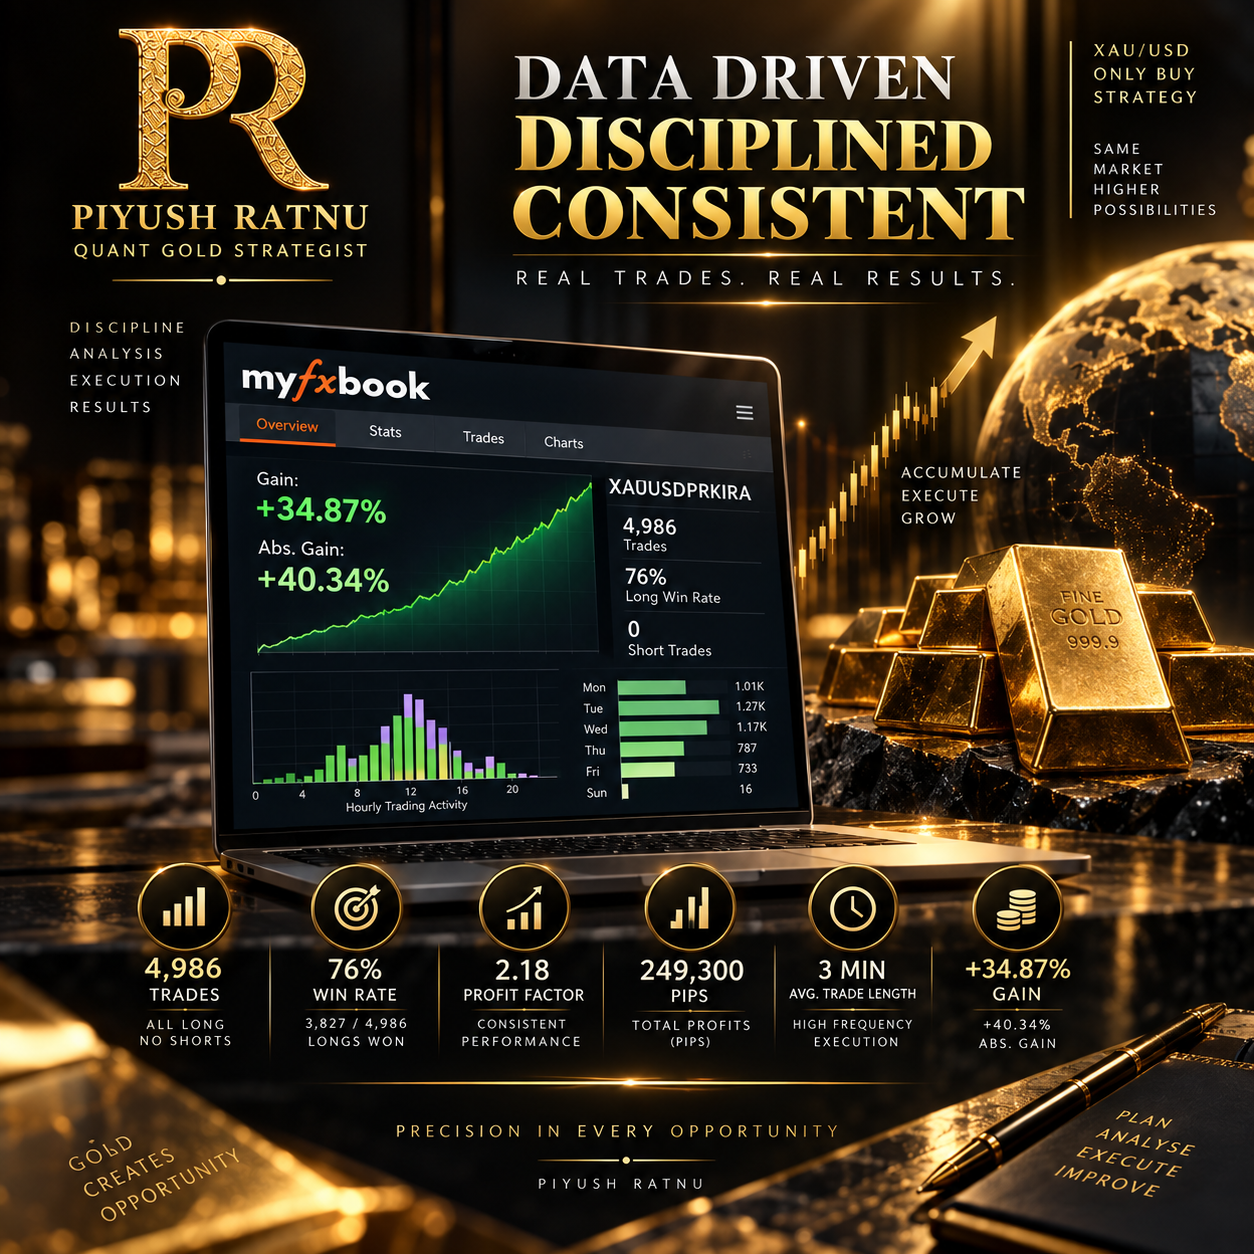 The Myfxbook statistics provide a substantial sample for examining that methodology. They show 4,986 trades, 60.40 lots traded, 249,300 pips, a 76% long win rate and a 2.18 Profit Factor. The performance overview separately shows Gain of +34.87% and Absolute Gain of +40.34%.
The defining characteristic, however, is not simply the return. It is the way those results were produced.
4,986 Trades — and Zero Short Positions
The most distinctive statistic in the report is straightforward:
Longs: 4,986 trades
Longs Won: 3,827 / 4,986 — 76%
Shorts: 0
Shorts Won: 0 / 0
This means the dataset shown is not the product of alternating between long and short exposure whenever Gold changes direction. According to the supplied Myfxbook statistics, every recorded trade was a BUY position.
That is the practical expression of one of the central principles behind my approach:
Buy XAU/USD lows rather than shorting XAU/USD lows.
It is deliberately restrictive. A strategy that permits both directions has twice as many directional choices available to it. A long-only methodology must instead deal with bearish phases through entry selection, price mapping, patience, position management and recovery, rather than simply reversing direction and selling.
That makes the 4,986-trade sample particularly useful when evaluating the methodology.
76% Winning Long Trades: Accuracy Across a Large Sample
A high percentage on a handful of trades tells us relatively little. What interests me more is whether an approach can repeat its underlying logic across thousands of executions.
The supplied statistics report 3,827 winning long trades from 4,986 total long positions, which Myfxbook displays as 76%.
Approximately one quarter of trades therefore did not win. This is important because the objective of systematic trading should never be to create the impression that losses do not exist. They do.
The more meaningful question is whether the combination of winning frequency, winning amounts, losing amounts and trade management produces positive aggregate performance.
This is where another statistic becomes important: Profit Factor 2.18.
A profit factor above 1 indicates that gross profits exceeded gross losses over the measured sample; 2.18 indicates roughly $2.18 of gross profit for every $1 of gross loss, based on the platform’s calculation.
That provides more information about the system than win rate alone.
The Mathematics Behind the Trades
The statistics reveal several additional characteristics of the trading behaviour.
The average winning trade was 145.76 pips / $1.95, while the average losing trade was -266.21 pips / -$2.95.
This means the average loss was larger than the average win.
Viewed alone, that would be a weakness. But trading results are determined by the interaction between win frequency and payoff distribution, not by one number in isolation.
A strategy with smaller average winners can still generate positive expectancy when its winning frequency is sufficiently high and losses remain controlled at the portfolio level.
Myfxbook reports expectancy of 50.0 pips / $0.81 per trade for the supplied sample.
The methodology therefore depends heavily on maintaining a sufficiently high success rate. If the long win rate deteriorated materially while the average loss remained larger than the average win, performance characteristics could change considerably. This is one reason continuous monitoring is essential.
Best and Worst Trades: Transparency Matters
The MyFxBook also reveal the extremes.
The reported best trade was $60.49, while the worst trade was -$34.65.
Measured in pips, the largest winning trade was 1,889 pips, while the largest losing trade was -2,304 pips.
I believe showing both sides matters.
Performance analysis should not consist only of publishing the strongest trades. Losing trades, adverse excursions and weak periods are part of any genuine trading dataset. A transparent methodology should therefore be evaluated from the complete distribution rather than from selected screenshots of profitable entries.
 A High-Frequency Execution Profile
Another revealing statistic is the three-minute average trade length.
That tells us this is not simply a conventional long-term Gold strategy where a few positions are opened and held for weeks.
The system represented in these statistics operates through a much larger number of relatively short-duration executions.
With 4,986 trades and 60.40 cumulative lots, the methodology appears to divide exposure across many individual trades rather than relying entirely on a small number of oversized directional bets.
That is consistent with my broader approach of working around price zones, clusters, short-term opportunities and repeated execution.
When Does the Strategy Trade Most?
The hourly statistics provide another layer of insight.
Trading activity is heavily concentrated around the middle of the displayed hourly distribution. The largest bucket is approximately 1,200 trades around hour 13, followed by 756 around hour 12, 673 around hour 14 and 459 around hour 15.
This concentration suggests that trading activity is not distributed evenly throughout the day.
The weekday statistics tell a similar story.
The screenshots show approximately:
Monday — 1.01K trades
Tuesday — 1.27K trades
Wednesday — 1.17K trades
Thursday — 787 trades
Friday — 733 trades
Sunday — 16 trades
Tuesday represents the highest activity in the supplied weekday chart, followed by Wednesday and Monday.
This matters because Gold liquidity and volatility vary significantly across global sessions and around US economic releases. Myfxbook itself notes that XAU/USD is affected by macroeconomic indicators, central-bank policy, interest rates, sentiment and geopolitical developments.
Methodology: Price Mapping Before Execution
The numbers describe the outcome, but the methodology explains how I attempt to generate it.
My XAU/USD framework begins with price mapping.
Rather than seeing Gold at $4,300 and deciding emotionally whether it “looks bullish” or “looks bearish,” I prefer identifying zones before price reaches them. Those levels are then evaluated against liquidity, technical structure, session behaviour, macroeconomic catalysts and correlations.
I monitor factors including DXY, US Treasury yields and USD/JPY, particularly around high-impact US economic events.
The objective is not to use correlations as automatic BUY signals. It is to establish whether independent markets support the price structure I am observing in Gold.
From there comes execution.
Analysis → Price Map → Confirmation → BUY Execution → Management → Exit → Validation
This is the process I want the statistics to represent.
Why No Shorts?
My decision to operate this methodology without short positions is intentional.
Gold can fall rapidly. There will inevitably be occasions where a short position would have generated profit during a decline.
But a systematic methodology does not need to participate in every market move.
My focus is instead on allowing downward movements to bring XAU/USD toward lower predefined buying zones. Once price enters an area supported by my analytical framework, I look for BUY opportunities rather than automatically extrapolating the decline and selling after Gold has already fallen substantially.
This does not mean buying every decline. A long-only strategy can be particularly vulnerable during sustained bearish trends, and the statistics shown do not guarantee how the approach will perform under different future market regimes.
The discipline lies as much in determining where not to buy as in deciding where to enter.
Performance Should Be Measured, Not Claimed
The performance overview supplied for this account shows:
Gain: +34.87%
Absolute Gain: +40.34%
Those numbers are accompanied by a much deeper dataset: thousands of trades, winning and losing transactions, trade duration, lots, pips, expectancy, profit factor and hourly/day-of-week distributions.
That is the standard I prefer for evaluating trading performance.
Myfxbook provides account-performance tools that can display measures such as gain, drawdown, daily and monthly percentages and equity/gain charts. Its broader XAU/USD data tools also cover historical data, volatility, correlations, indicators and patterns.
Accuracy Through Repetition, Not Perfection
The central message from these statistics is not that every BUY works.
The dataset itself disproves such a claim.
Instead, the methodology is built around repeatability.
Across 4,986 long-only trades, the supplied report records 3,827 winning longs, a 76% long win rate, 249,300 pips, 60.40 lots, positive expectancy and a 2.18 Profit Factor, alongside the displayed +34.87% Gain.
For me, that is the more useful definition of trading accuracy: not perfection on every position, but a methodology that can be documented, measured and repeatedly tested against the market.
One market: XAU/USD.
One directional philosophy: BUY.
Thousands of executions.
One measurable methodology.
Analyse the market. Map the price. Buy the opportunity. Measure the result.
— Piyush Ratnu
Quant Gold Strategist
XAU/USD Analysis • Algorithms • Research